
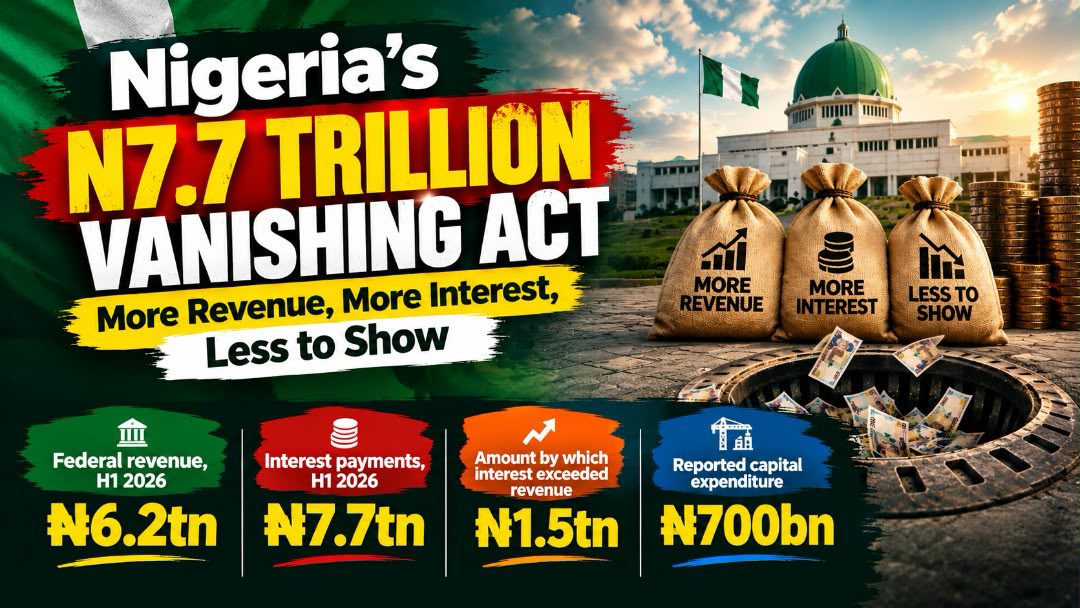
Nigeria spent N7.7 trillion on interest in the first half of 2026, more than the N6.2 trillion it earned in revenue. Over the same period, capital expenditure fell to about N700 billion, so the narrower deficit may owe more to spending cuts than to real fiscal progress. Until government shows what its borrowing has built, rising revenue will not turn into public value.
Nigeria’s interest payments now exceed federal revenue
What makes Nigeria’s fiscal situation particularly troubling is the contradiction between the government’s growing financial obligations and citizens’ expectation that public revenue should translate into tangible public value. The Federal Government paid creditors more in interest than it collected in revenue, which leaves most Nigerians confused. That is a N1.5 trillion gap before accounting for the government’s many other responsibilities.
Capital expenditure falls to N700 billion
The more disturbing figure lies elsewhere. While the government spent N7.7 trillion on interest, capital expenditure dropped to about N700 billion from N2.2 trillion in the same period of 2025, according to the World Bank’s October 2026 Nigeria Development Update.
The contrast is brutal. The interest bill was roughly 11 times reported capital expenditure. In a country struggling with infrastructure deficits, expensive electricity, inadequate public services and businesses fighting to remain productive, this raises a question the government cannot afford to evade: what does fiscal stability mean when the cost of servicing yesterday’s borrowing threatens to overshadow investment in tomorrow’s economy?
One point deserves to be made clearly. The figures do not establish that debt interest alone caused capital expenditure to fall, and not every reduction in public investment represents waste. But the gap is too significant to be buried beneath reassuring claims about improved revenue collection or a narrowing fiscal deficit.
Revenue growth vs rising debt interest payments
Nigeria’s revenue increased from N3.6 trillion in the first half of 2025 to N6.2 trillion in the first half of 2026, an increase of approximately 72 per cent. That is substantial progress. Meanwhile, interest payments jumped from N5.6 trillion to N7.7 trillion, a rise of about 37.5 per cent. The government may be collecting more revenue, but the cost of servicing its debts continues to eat into its earnings, leaving little room to meet other pressing needs.
For every N100 collected in federal revenue, approximately N124 went towards interest. This does not mean Nigeria is necessarily insolvent, nor that interest payments are the only claim on public finances. It does, however, expose a serious imbalance between the government’s revenue capacity and its debt obligations.
How debt service constrains public investment
When a government’s financial obligations grow so large that its freedom to invest becomes constrained, the consequences do not remain inside the Treasury. They travel into unfinished roads, unreliable infrastructure, constrained public services and a business environment in which firms must absorb costs that more productive public investment could help reduce.
The real scandal, therefore, is not simply that Nigeria owes money. It is that the country must now answer a harder question. Are its borrowing decisions building an economy capable of carrying the debt, or are the costs of past and present borrowing progressively narrowing the resources available to build that economy?
Is Nigeria’s borrowing productive?
Making a clear distinction here matters, because borrowing is not necessarily irresponsible. Governments can use loans to finance infrastructure and other productive investments that create jobs, strengthen the economy and generate the revenue needed to repay the debt.
In many cases, the danger emerges when debt of N166.79 trillion accumulates without commensurate growth in the economy’s ability to service it, or when the returns on borrowed funds remain unclear. At that point, debt ceases to be merely a financing instrument and becomes a growing claim on future public resources.
Nigeria’s fiscal figures demand that this possibility be examined without sentiment or political convenience.
Narrower fiscal deficit: progress or spending cuts?
One of the encouraging points in the World Bank’s assessment is that the Federal Government’s fiscal deficit is getting smaller. The World Bank says the deficit fell from N11 trillion in the first half of 2025 to N9.9 trillion in the same period of 2026. It also warns that a drop in capital spending and fewer capital-intensive projects are part of why Nigeria’s fiscal position looks better.
That qualification deserves more attention than it has received in the broader conversation about economic reform.
A lower budget deficit can indicate stronger public finances when it results from higher revenue, more efficient expenditure and reduced financing needs, which means less borrowing. The interpretation changes when the improvement comes with a steep contraction in capital spending.
How lower capital spending slows growth
Delayed road projects leave businesses paying more to move goods. Weak electricity infrastructure forces manufacturers to spend more on alternative power. Poor transport networks make it costlier to get farm produce to market, while insufficient investment in healthcare and education weakens human capital and productivity. These costs add up and slow growth.
These consequences can eventually undermine the very revenue growth the government needs to reduce its dependence on borrowing.
The point is not that every naira allocated to capital expenditure must be spent regardless of project quality. Nigeria has a legitimate responsibility to eliminate wasteful contracts, abandoned projects, inflated costs and politically motivated expenditure. But cutting productive investment is not a substitute for fixing the fiscal system.
The government needs to explain whether the drop in capital spending reflects insufficient revenue, different spending priorities or a deliberate effort to narrow the deficit. It must also say which projects were affected, which bills remain unpaid and how the cuts will affect the economy in future.
Without this explanation, a narrower deficit risks becoming an incomplete measure of progress.
Why revenue gains are not yet fiscal breathing room
It would be misleading to portray Nigeria’s fiscal position as though nothing has improved. Revenue increased substantially between the first halves of 2025 and 2026, and the reported fiscal deficit narrowed. The World Bank also identified stronger corporate tax and independent revenue receipts, along with improved oil receipts, as factors supporting revenue performance.
These gains matter. When a country collects more revenue locally, it is better placed to fund public services and rely less on borrowing. Better tax management and improved compliance can also strengthen government finances and make the economy more resilient.
Meanwhile, the persistence of an interest bill exceeding federal revenue shows how difficult it is to convert those gains into meaningful fiscal breathing room.
How reliable is Nigeria’s revenue growth?
Nigeria’s problem is not simply whether it can collect more money. It is whether the revenue it collects can sustainably cover its obligations while leaving sufficient resources for public investment and essential services.
Answering that requires a closer look at the composition and reliability of revenue. How much of the improvement comes from recurring tax receipts, and how much depends on oil prices, production volumes or one-off payments? Are independent revenues being collected consistently? Are public enterprises remitting what they owe? Are tax exemptions, revenue leakages and poor compliance costing the government money it could collect without putting more pressure on taxpayers who already pay what they owe?
These questions matter because temporary revenue gains cannot safely support permanent spending commitments. Nor can the government rely indefinitely on favourable oil-market conditions to finance obligations that continue regardless of the direction of global prices.
A sustainable fiscal plan should bring more people and businesses into the tax net, plug revenue leakages and make it easier for businesses to grow. Tax reforms must be fair and predictable, not simply a way of raising taxes that leaves households with less to spend or discourages businesses from investing.
Tax policy should strengthen the capacity of the economy to produce and earn, not merely extract more from an already strained productive sector.
Domestic borrowing costs and private-sector credit
The rising cost of domestic borrowing is another critical part of the story. The World Bank identified elevated domestic borrowing costs as a factor behind the increase in interest payments, and the implications extend beyond the government’s accounts.
This deserves scrutiny. When treasury bills and government bonds offer attractive risk-adjusted returns, banks and other investors may allocate more funds to government securities, depending on their liquidity needs, portfolio strategies, regulatory requirements and assessment of private-sector risks. Under certain conditions, this can make it more difficult or expensive for businesses to secure financing.
To be fair, the effect should not be exaggerated. Government securities provide legitimate investment opportunities, support liquidity management and help finance public expenditure. Banks do not automatically abandon private-sector lending simply because government instruments offer attractive yields.
Nevertheless, the balance between financing the government and financing productive enterprise deserves scrutiny in an economy where businesses already face high operating costs, infrastructure deficits and significant financing constraints.
A manufacturer deciding whether to expand production does not assess interest rates in isolation. It must weigh electricity, logistics, foreign-exchange exposure, taxes and demand alongside the cost of capital. For small and medium-sized enterprises, expensive credit can make an otherwise viable investment commercially unattractive and push firms out of business.
The more concerning part is that when productive firms cannot obtain affordable financing, their ability to expand output, employ workers and generate taxable income is weakened. If the government simultaneously struggles to finance the infrastructure that would reduce their operating costs, the economy faces a damaging combination of expensive private production and expensive public financing.
The debt and interest cycle Nigeria must break
This is the cycle Nigeria must break. When borrowing becomes more expensive, the government spends more on interest and has less to invest in infrastructure and other productive sectors. Poor infrastructure then holds back productivity and business growth, which makes it harder for the government to generate more revenue.
The solution is not to force interest rates down while ignoring inflation and economic realities. It is to tackle the problems that make borrowing expensive in the first place, which will eventually create a friendlier environment for investment.
This means restoring confidence in the government’s finances, cutting avoidable borrowing, managing debt better and ensuring that borrowed money is put to good use. The government must also work more closely with the CBN on economic policy, while allowing the bank to make monetary decisions independently.
What has Nigeria gained from its borrowing?
Perhaps the biggest question is one Nigeria has not seriously answered: what has the country actually gained from all the money it has borrowed over the years?
The total amount of public debt matters, but it cannot by itself determine whether borrowing has been productive. A country may borrow heavily and still strengthen its economy if the funds finance viable infrastructure, productive assets and investments that expand future revenue. Another may borrow less but struggle if the money is poorly allocated or fails to generate lasting economic benefits, which appears to be Nigeria’s present case.
Nigeria needs a more rigorous public accounting of the relationship between borrowed funds and completed projects.
For major debt-financed projects, citizens should be able to know the amount borrowed, the project’s original cost, the funds released, the completion status, the economic benefits expected and the actual results delivered. Where projects remain incomplete or significantly exceed their budgets, the responsible authorities should explain why and identify corrective action.
This is not simply an argument for better documentation. It is a demand for a different standard of accountability.
If borrowing is justified on the grounds that it will expand economic capacity, the government must demonstrate that the promised capacity is materialising. If a railway is financed, what improvements have occurred in transport efficiency and freight movement? If power infrastructure receives substantial funding, what measurable gains have followed in electricity reliability and productive output? If agricultural projects are financed, what has happened to yields, distribution costs and rural incomes? The same standard should apply to the road projects of the Minister of Works, David Umahi.
The fact remains that not every project will generate direct revenue for the government, and some investments produce social benefits that cannot be measured solely in cash. Even so, the public deserves a credible account of the economic and social returns that justify the debt incurred.
Without such scrutiny, successive administrations can inherit large repayment obligations while citizens struggle to identify the assets and benefits created by the borrowing. That is the accountability gap Nigeria must close.
Debt transparency reforms Nigeria needs
The Federal Government and the National Assembly must move beyond treating budget approvals, revenue targets and borrowing authorisations as achievements in themselves.
A budget is a plan. Revenue is a resource. Borrowing is a financing decision. None is an economic outcome until public resources are translated into completed projects, functioning services and measurable improvements in productivity and welfare.
The government needs to show clearly how much it earns, how much goes into interest and debt repayments, how much it borrows and what is actually spent on capital projects. These figures should be published regularly, in a way that allows ordinary Nigerians, journalists, researchers and lawmakers to see whether government plans match what is delivered.
The Federal Ministry of Finance, the Debt Management Office and the Budget Office should explain how the N7.7 trillion interest bill was arrived at. Nigerians deserve to know how much went towards domestic and foreign debt, when the debts fall due and what it will cost to refinance existing loans.
The government must also publish a clear explanation of the decline in reported capital expenditure, identifying delayed projects, outstanding contractor payments and the investments protected as priorities.
National Assembly’s role in debt oversight
The National Assembly, for its part, must scrutinise borrowing proposals not merely by asking whether the government can raise funds. It must not become a rubber stamp in the 10th Assembly, and should instead examine the purpose, terms, risks and expected returns of the financing. Legislative oversight must continue beyond approval to include implementation and the verification of results.
Debt management should prioritise prudent financing, transparent terms, careful maturity planning and a credible strategy for reducing unnecessary dependence on expensive short-term borrowing. Refinancing decisions must be assessed against actual market conditions, currency exposure and the risks of replacing one obligation with another.
At the same time, capital expenditure should be protected where projects offer strong economic and social returns. This does not mean spending without discipline. It means distinguishing productive investment from waste, and treating project completion and value for money as essential parts of fiscal reform.
The objective is not simply to spend more. It is to ensure that the country gets more development value from every naira it spends or borrows.
Nigeria’s 4.2% GDP growth: cautious optimism
Nigeria’s economic outlook contains grounds for cautious optimism. The World Bank reported real GDP growth of 4.2 per cent in the first half of 2026, compared with 3.9 per cent and 3.5 per cent in the corresponding periods of 2025 and 2024, respectively. It also noted improvements in fiscal and external conditions.
These developments should be acknowledged. Macroeconomic stability matters because persistent instability discourages investment, complicates business planning and undermines the purchasing power of households.
But growth and stability are not ends in themselves. Their ultimate value lies in the economic opportunities they create, the services they support and the improvements they deliver to people’s lives.
An economy can grow and still leave businesses struggling with poor infrastructure, few jobs and high production costs if the government fails to invest enough in areas that support growth. The same goes for government revenue. Collecting more money means little if much of it goes towards paying for debts built up over the years, leaving less to improve public services.
Judge fiscal reform by results
The relevant test is not whether one indicator has improved. It is whether the fiscal system is becoming more capable of sustaining growth, meeting its obligations and delivering public value at the same time.
Nigeria must resist the temptation to celebrate revenue growth while overlooking the cost of borrowing, or to present a narrower deficit as conclusive proof of fiscal success without explaining the contraction in capital spending. Reform must be judged by its combined results.
Ultimately, Nigeria’s N7.7 trillion interest bill is not merely an accounting problem for the Treasury. It is a test of whether the country’s borrowing is building the economy it will need to repay it, and Nigerians deserve a clear answer.
Blaise, a journalist, PR professional, and opinion writer with Confiance News. He writes from Lagos and can be reached via: blaise.udunze@gmail.com
- capital expenditure
- Confiance News
- federal revenue
- fiscal deficit
- interest payments
- Nigeria capital expenditure drop 2026
- Nigeria debt
- Nigeria debt service burden
- Nigeria economy
- Nigeria fiscal deficit narrows N9.9 trillion
- Nigeria interest payments exceed federal revenue
- Nigeria N7.7 trillion interest payments
- Nigeria public debt N166.79 trillion
- World Bank Nigeria
- World Bank Nigeria Development Update October 2026



Leave a comment