
•Ripple seeks direct access to Federal Reserve payment systems.
•Validates blockchain as critical financial infrastructure, encouraging firms like Circle to pursue similar charters.
•Direct access to central bank systems threatens correspondent banks’ revenue, pushing them to adopt blockchain solutions.
•Enables seamless integration of crypto and fiat, supporting tokenized assets and CBDC development.
Ripple, a San Francisco-based blockchain payments firm, has applied for a national banking charter with the U.S. Office of the Comptroller of the Currency (OCC), signaling a bold move to integrate digital assets with traditional finance.
Confiance News gathered that this strategic step, announced on July 3, 2025, aims to position Ripple as a regulated financial institution, bridging the gap between cryptocurrency and mainstream banking. The implications of this move ripple across the crypto/blockchain sector, commercial banks, and the broader financial ecosystem.
Why Ripple is Seeking a Banking License Ripple’s application is driven by its ambition to legitimize and expand its role in global finance. By securing a national banking charter, Ripple would gain direct access to the Federal Reserve’s payment infrastructure, enabling faster and cheaper transaction settlements without relying on intermediary banks.
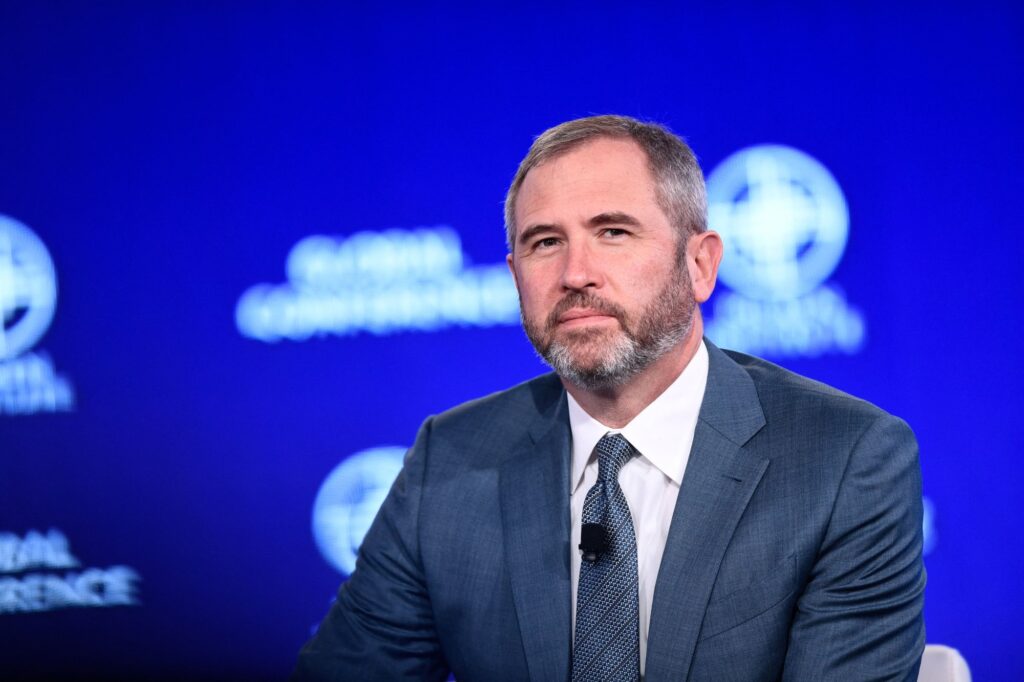
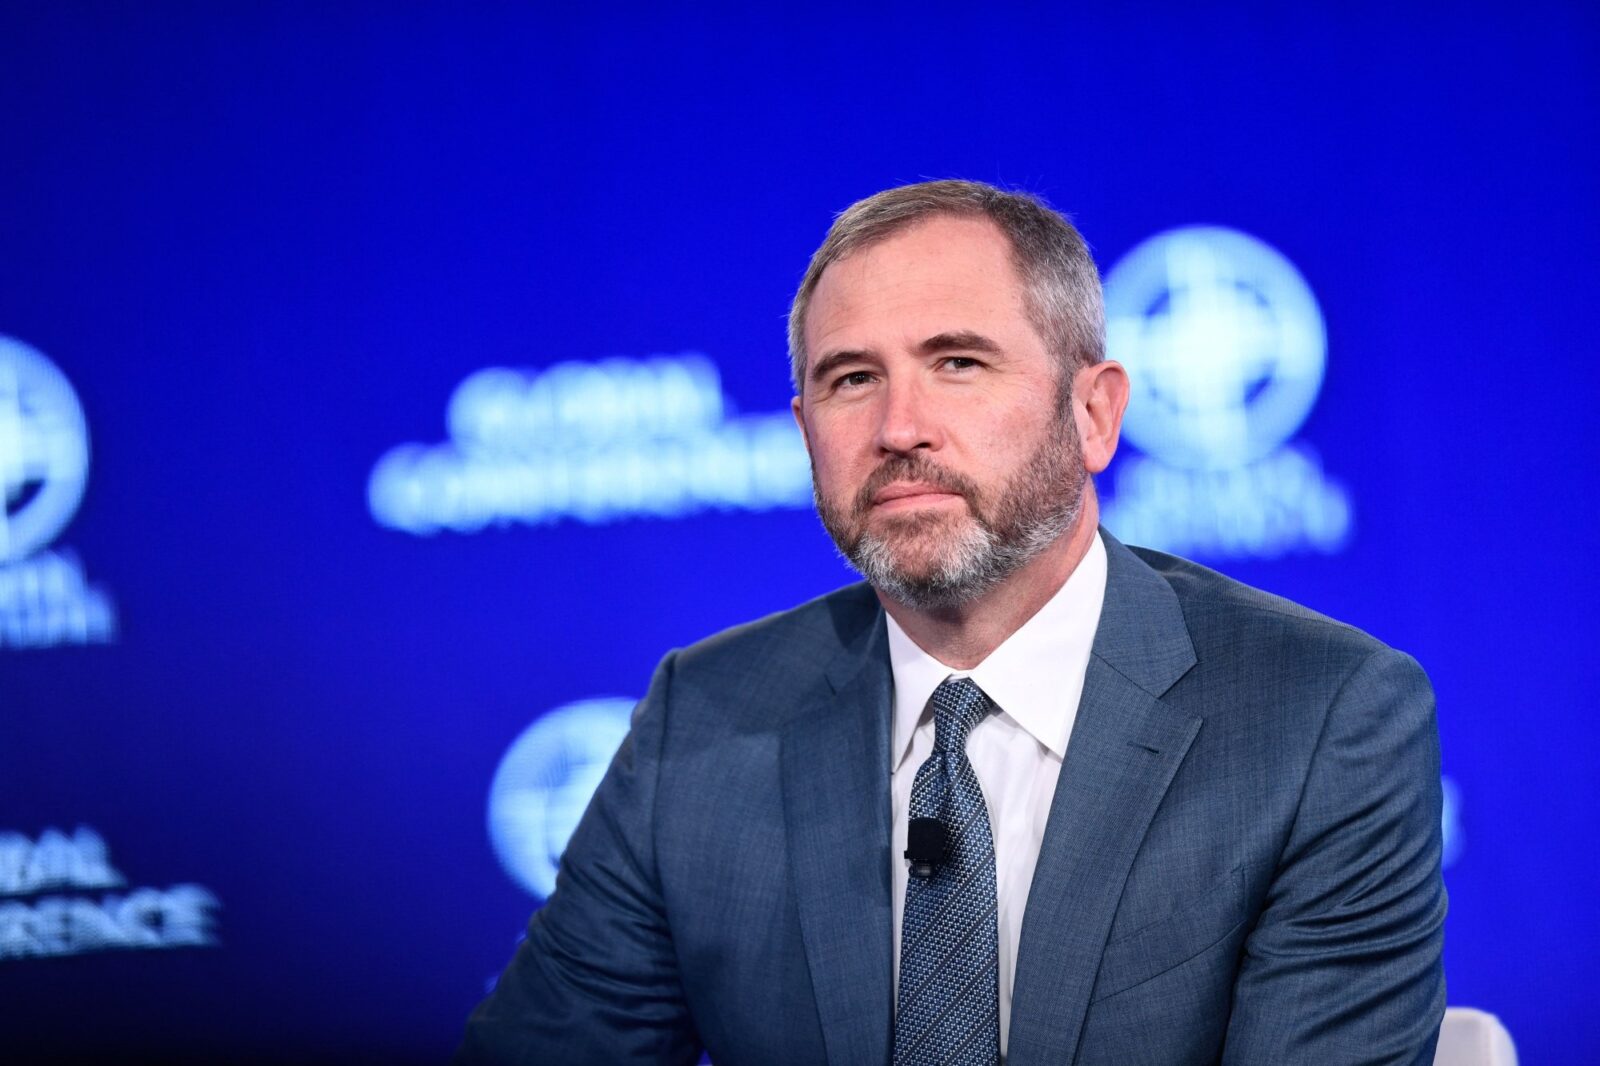
Reacting to Ripple’s banking license application, Chief Executive Officer (CEO) of Ripple, Brad Galinghouse, said on X, “True to our long-standing compliance roots, @Ripple is applying for a national bank charter from the OCC. If approved, we would have both state (via NYDFS) and federal oversight, a new (and unique!) benchmark for trust in the stablecoin market.”
This aligns with Ripple’s core mission of streamlining cross-border payments using its XRP Ledger and native cryptocurrency, XRP.
The license would also allow Ripple to offer services like lending and custody, integrating its USD-backed stablecoin, RLUSD, with traditional banking operations. CEO Brad Garlinghouse emphasized this move as a response to regulatory clarity post the SEC lawsuit resolution in 2023, positioning Ripple to operate as a trusted entity within the financial system.
Implications for the Crypto/Blockchain Sector Ripple’s pursuit of a banking license is a landmark for the crypto industry. It validates blockchain’s potential as a core financial infrastructure, encouraging other crypto firms like Circle and Coinbase to seek similar charters. This could accelerate institutional adoption of digital assets, boosting credibility and liquidity.
The integration of XRP and RLUSD into regulated banking could drive structural demand for cryptocurrencies, reducing reliance on speculative trading. However, it may challenge the decentralized ethos of some blockchain advocates, as Ripple’s centralized approach aligns more closely with regulatory frameworks.
Impact on Commercial Banks
For commercial banks, Ripple’s move poses both opportunities and threats. Banks using RippleNet, like Santander and Bank of America, could benefit from enhanced blockchain-based payment solutions, reducing costs by up to 60% compared to traditional systems like SWIFT. However, Ripple’s direct access to central bank systems could bypass correspondent banking, threatening intermediaries’ revenue streams. This may push banks to accelerate blockchain adoption to remain competitive, potentially reshaping their operational models.
Transforming the Financial Ecosystem Ripple’s banking license could redefine the financial ecosystem by integrating crypto and fiat systems. It would enable seamless cross-border transactions, tokenized assets, and central bank digital currency (CBDC) development, as seen in Ripple’s pilots with nations like Bhutan and Palau. This convergence could enhance financial inclusion, reduce transaction costs, and unlock capital trapped in pre-funded accounts, estimated at $10 trillion globally.
However, regulatory scrutiny and competition from stablecoins and CBDCs may temper Ripple’s impact. In conclusion, Ripple’s banking license pursuit is a strategic leap toward mainstreaming blockchain in finance. It strengthens the crypto sector’s legitimacy, challenges traditional banking models, and paves the way for a hybrid financial ecosystem, balancing innovation with regulation.


Leave a comment